Business
Google just ran out of free cash for the first time in a decade, on purpose
By Ashish Kumar · 4 August 2026 · 4 min read
Alphabet just posted one of its best quarters in years. It also ran its cash flow negative for the first time in a decade, on purpose, and investors punished the good news anyway.
By almost every normal measure, Alphabet's second quarter of 2026, reported on July 22, was a strong one. Revenue climbed 24% year over year to $119.8 billion, beating the roughly $116.5 billion analysts expected. Earnings per share came in at $9.11, far ahead of the $2.88 consensus. Operating margins expanded to 34%. Google Cloud, the company's enterprise AI infrastructure business, grew revenue 82% to $24.8 billion, with a backlog that reached $514 billion and existing customers exceeding their contracted spending commitments by more than 50%.
Alphabet's stock fell 7% anyway. The reason wasn't the quarter that had just happened. It was the one still to come.
The number that actually moved the market
Alongside the results, Alphabet raised its full year capital expenditure guidance to $195 to $205 billion, up from a prior range of $180 to $190 billion, almost entirely to fund AI data centers, chips and infrastructure. Quarterly capex alone reached $45 billion in Q2, up from $36 billion in Q1. To help fund it, Alphabet said it would issue up to $85 billion in new stock specifically "to scale AI infrastructure and global compute."
The consequence showed up in a number Alphabet has not reported in roughly ten years: free cash flow, the cash left over after running the business and paying for investments, turned negative, at -$5.9 billion. CFO Anat Ashkanazi attributed the swing directly to the capex increase.
Why this is a stranger story than "big tech overspends on AI"
That framing is familiar and mostly wrong here. Alphabet isn't spending blindly hoping demand shows up later. Google Cloud's backlog of $514 billion and customers already spending 50% more than they committed to are unusually concrete signals of real, current demand, not speculative future demand. CEO Sundar Pichai said the company is "winning new customers, more than doubling our acquisition velocity." This is closer to a company that is capacity constrained, unable to build data centers fast enough to keep up with paying customers, than one betting on a market that might never arrive.
The actual tension is different: a company famous for decades as a cash generating machine, one whose free cash flow funded stock buybacks and cushioned every downturn, has voluntarily traded that cushion away, mid-boom, to avoid being the hyperscaler left without enough compute to sell.
A simple way to picture it
Imagine a bakery so popular that the line is out the door every morning, and instead of quietly enjoying record sales, the owner takes out a large loan to buy a second oven, a walk in freezer and a delivery van, all at once, because turning away customers today means losing them to the bakery across the street tomorrow. The spending isn't reckless. It's a bet that under-building costs more than over-building, in a market moving this fast.
"We're winning new customers, more than doubling our acquisition velocity." - Sundar Pichai, Alphabet CEO, on Google Cloud's growth
The honest catch
The market's nervousness isn't baseless. Analyst Chris Ballard described the sector as "transitioning from AI hype to monetization discipline," meaning investors now want proof that this capex converts into durable profit, not just growth. Alphabet's own backlog and cloud growth numbers are the strongest such proof available among the major AI infrastructure spenders right now, but a $514 billion backlog is a promise of future revenue, not cash already banked, and multi-year AI infrastructure bets carry real risk if enterprise AI adoption slows or if cheaper compute alternatives emerge before Alphabet's spending is repaid. A negative free cash flow quarter is sustainable for a company with Alphabet's balance sheet. It would be a five alarm fire for almost anyone else.
Alphabet just proved its AI business works well enough to sell out its own capacity. The market's real question isn't whether the demand is genuine. It's whether spending faster than you earn, even for good reasons, is a habit any company, even this one, can sustain indefinitely.
Watch on Qrio
One-minute reels on this and related topics.
 ▶ 1:21
Business
Is AI a bigger bubble than the dot-com crash?
by yieveberlins
 ▶ 2:51
Finance
How Berkshire Hathaway really makes money
by Dulma 🦋
 ▶ 1:54
Business
Anthropic's IPO paperwork, explained
by PeterStewieStartup
 ▶ 1:46
Business
Anthropic's IPO filing: a profit and a $66 billion loss
by Finance Explained in 90 Seconds
More business stories
Business
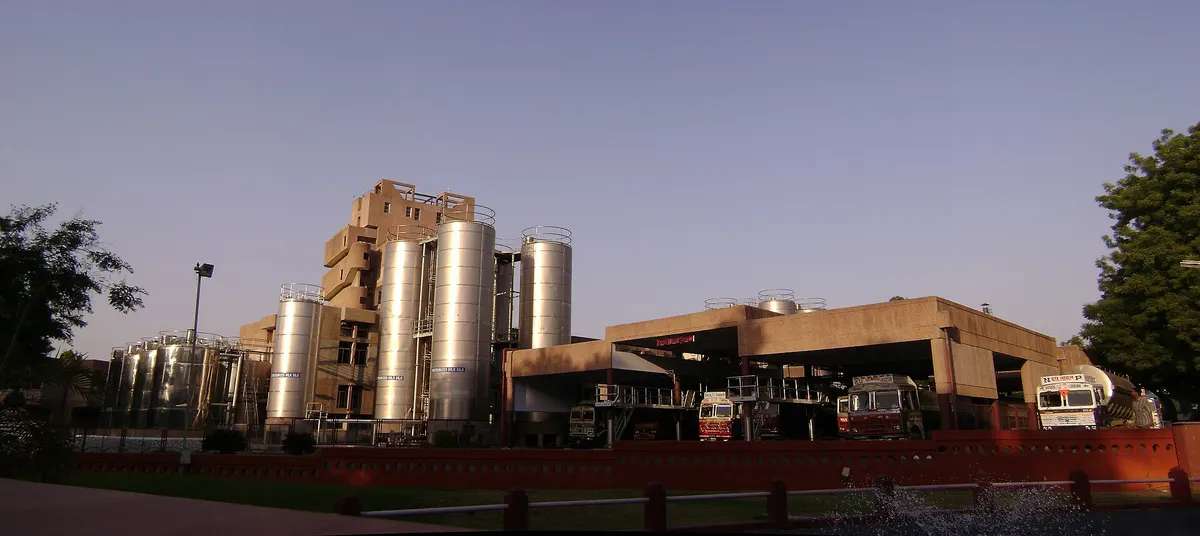
Your milk costs up to ₹4 more from today. Here is who gets the extra money
Amul and Mother Dairy raised milk prices by ₹2 to ₹4 per litre from November 12, 2026. Amul Taaza toned milk is up ₹2 (3.3%) and Amul Gold is up ₹4 (5.5%) across India. In Delhi-NCR, Mother Dairy full cream milk goes from ₹72 to ₹76 a litre and toned milk from ₹60 to ₹62. Both dairies blame costlier fodder, cattle feed, packaging and fuel after an uneven monsoon, and both say most of what you pay goes back to farmers: about 80% for Amul, 75% to 80% for Mother Dairy. It is the second hike since May, and it comes two weeks after Karnataka raised Nandini milk by ₹8.
12 November 2026 · 6 min read
Business
Razorpay plans to list for a third less than its 2021 value, after paying $150 million to come home
Razorpay, the Bengaluru company behind the checkout page on many Indian websites, has reportedly received SEBI's approval for its IPO. Reports put the issue at roughly ₹5,000 to 6,500 crore and the valuation at about $5 billion, with a listing expected between January and March 2027. That is about a third below the $7.5 billion it was valued at in 2021. Razorpay had first moved its parent company from the US to India, a switch reported to have cost about $150 million in taxes. It grew revenue 65% in FY25 to ₹3,783 crore but booked a loss tied to one-time costs. Neither Razorpay nor SEBI has confirmed the approval publicly.
5 November 2026 · 7 min read