India Macro
Amid Everything Else India is Juggling, an Unexpected Problem Just Crossed a Line No One Saw Coming
By Ashish Kumar · 9 June 2026 · 7 min read
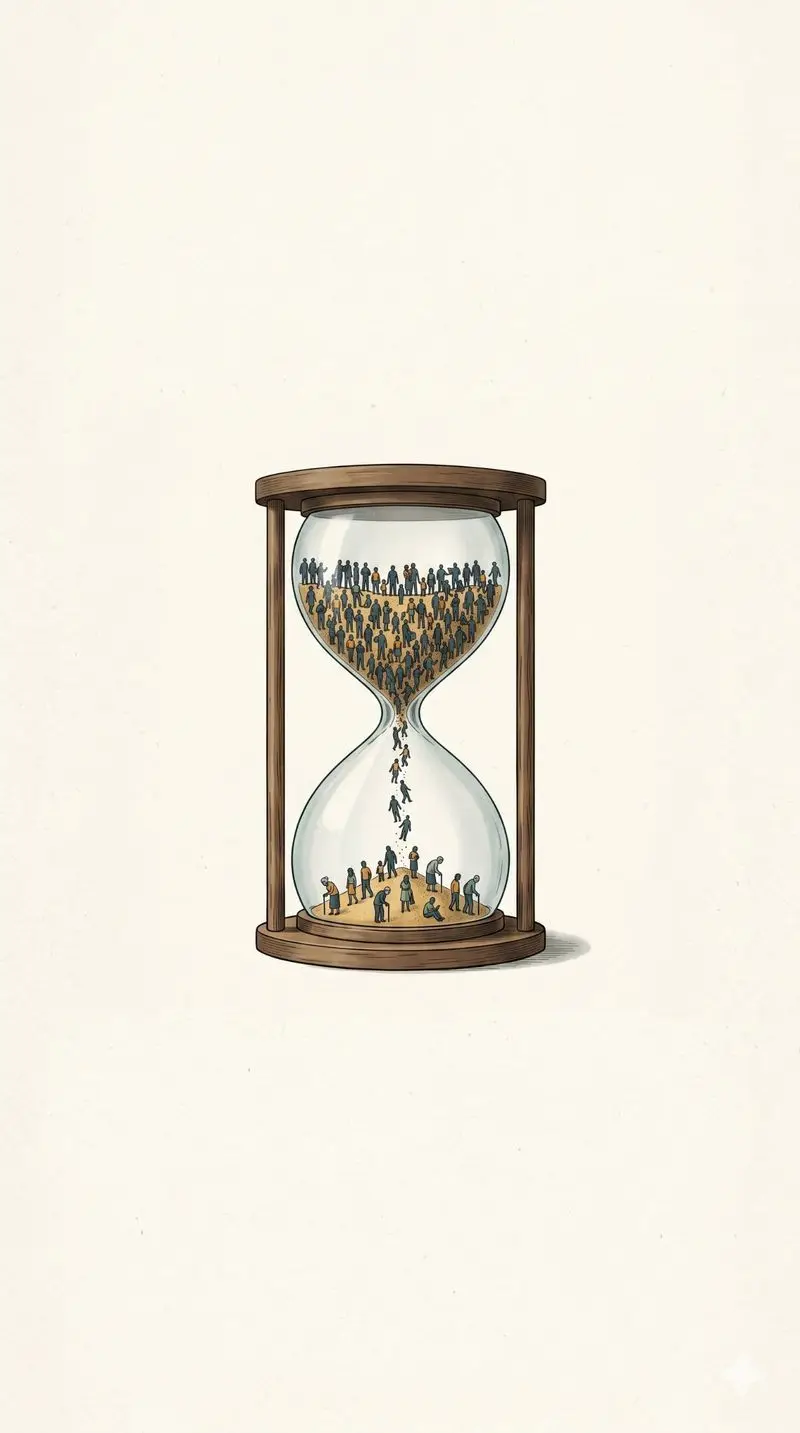
For the First Time in Its History, India Cannot Replace Its Own Population. The World Is Watching Closely.
The number that changed the story
In June 2026, India's government released its annual population report, and inside it was a number that quietly ended an era. India's total fertility rate, the average number of children a woman has in her lifetime, had fallen to 1.9. To keep a population stable, you need 2.1, one to replace the mother, one to replace the father, and a fraction to account for children who do not survive to adulthood. India had dropped below that line for the first time in its recorded history. The country that the entire world expected to be the last great source of young workers, the nation that overtook China as the most populous on earth, can no longer replace its own people through birth. The Economist called it a baby bust and a warning to the world. Elon Musk amplified it to hundreds of millions. And for once, the global alarm was not an overreaction.
The numbers behind the shift:
- India's fertility rate fell from 2.3 a decade ago to 1.9 in 2024, a drop of nearly 20 percent in ten years.
- Because India has more boys born than girls, its true replacement rate is closer to 2.2 than 2.1, which means India is even further below the line than the headline suggests.
- Delhi's fertility rate is just 1.2, lower than Finland or France. Kolkata, Chennai, and Kerala sit around 1.3.
- India's most productive generation was born back in 2001, when 29 million babies arrived. By 2024, that had fallen to roughly 23 million. The peak is already behind us.
The clock that started 25 years ago
Here is the part most people get wrong, and it is the key to the whole story. When people hear that India's population will keep growing for another 30 years, peaking around 1.7 billion by the 2050s, they assume there is no urgency. But** population growth and the supply of young workers are two different clocks.** The population keeps rising for decades purely because people are living longer, not because more babies are being born. The clock that actually matters for the economy, the number of young people entering the workforce, peaked a quarter of a century ago. As Sanjeev Sanyal, a member of the Prime Minister's economic council, has bluntly pointed out, the generation now powering India's economy is the largest the country will ever have. Every generation behind it is smaller. The famous demographic dividend, the young workforce that global investors bet on for two decades, has a visible expiry date, and the meter started running in 2001.
India's population will keep growing for 30 years. Its supply of young workers peaked 25 years ago. Those are not the same clock.
What happened to the four countries that went first
India is not the first to cross this line, and the four countries that went before it split into two very different fates. Three of them got rich before they got old. Japan fell below replacement in the 1970s, but it was already one of the wealthiest nations on earth, and although its population has been shrinking since 2009, it had the hospitals, pensions, and savings to manage the decline. South Korea crossed the line in the 1980s from a position of growing prosperity. Its fertility rate has since collapsed to 0.72, the lowest in the world, meaning each generation is barely a third the size of the one before, but it built its wealth first. China is the most recent, ageing so fast after its one-child policy that the pension fund of one northern province, Heilongjiang, has already gone bankrupt, but only after three decades of breakneck growth lifted hundreds of millions out of poverty. ** All three reached this point with money in the bank. The fourth country is the warning. Thailand fell below replacement in 1991, when it was still a poor, developing nation.** Its fertility rate has since dropped to around 1.2, as low as any rich country, and its workforce began shrinking in 2022. But Thailand never became wealthy. Its economy grew less than 2 percent a year between 2015 and 2024, and it is now stuck in what economists call the middle-income trap: too old to grow quickly, too poor to comfortably support its rising number of elderly. Thailand grew old before it grew rich, and it is now living the consequence, an ageing population it cannot easily afford on an income that stopped climbing.
India's income per person is under $3,000. When Japan reached this point, it was many times richer. India is attempting the same demographic transition not from Japan's position of strength, but from something much closer to Thailand's position of vulnerability.
The phrase that haunts every economist looking at India's data is exactly this: the country risks growing old before it grows rich, and Thailand is the live example of what that actually looks like.
The two Indias pulling in opposite directions
What makes India's case unique is that it is really two countries with two completely different futures. The south and west, Kerala, Tamil Nadu, Delhi, Karnataka, the wealthy, educated, urban India, already has fertility rates resembling Japan or Italy. The north and east, Bihar at 2.9, Uttar Pradesh at 2.6, the poorer, younger India, is still growing. For years this gap was India's safety valve: young workers from Bihar and UP migrated to fill jobs in Bangalore and Mumbai. But it is creating a political earthquake. India is due to redraw its parliamentary seats based on population, and the southern states that successfully controlled their fertility now fear losing seats and federal money to the northern states that did not. The states that did what the country asked of them feel they are about to be punished for it. Demography in India is no longer just economics. It is becoming a fight over political power itself.
What India can actually do, and what will not work
The instinct of worried governments is to pay people to have babies, and India has started. Andhra Pradesh now offers cash for a third or fourth child, reversing decades of "we two, our two" family planning. But the evidence from everywhere this has been tried is discouraging. South Korea spent over $200 billion trying to raise its birth rate and watched it fall to the lowest on earth anyway. Cash incentives produce, at best, a tiny temporary bump. They do not reverse the deep forces, education, urban living, the rising cost of raising a child, and the changing aspirations of women, that drive fertility down. And it means bringing more women into the workforce, where India ranks among the lowest of any major economy, because the surest way to soften an ageing crisis is to have more of your existing adults earning and contributing. India was handed the largest, youngest workforce in human history and one generation to use it well. The countries that went before India had more money and still struggled. India has less money and less time. What it does in the next decade with the young people it already has will decide whether 1.9 becomes a footnote or a turning point. The babies who will not be born are no longer the question. The ones already here are.
So the honest path forward is not about making more babies. It is about making the most of the large young generation India still has, because that window closes within 10 to 15 years. It means fixing an education system that currently produces graduates who cannot find work, so today's youth bulge does not become tomorrow's frustrated, underemployed middle-aged population. It means building healthcare and pension systems now, before 200 million Indians cross the age of 60, which will happen within two decades.
Watch on Qrio
One-minute reels on this and related topics.
 ▶ 2:03
Finance
How Australia went 29 years without a recession
by yieveberlins
 ▶ 1:46
Business
Anthropic's IPO filing: a profit and a $66 billion loss
by Finance Explained in 90 Seconds
 ▶ 1:40
Geopolitics
How China overtook the US as the world's trading partner
by Jake Explains
 ▶ 1:31
Geopolitics
Russia's Dead Hand: the system built to strike back
by The Theorist
More india macro stories
India Macro
Onions doubled in a year and your EMI just went up. Four myths about India's inflation jump
India's retail inflation rose to 5.54% in September 2026, its highest in almost two years, driven by food. Onion prices were up 108% from a year earlier. In October the RBI raised its repo rate by 0.25 points to 5.50%, its first hike since 2023, and said rate cuts are off the table for now. Several banks raised their repo-linked loan rates by the same 0.25 points from October 8. October's inflation number comes out on November 12 and ICRA expects it to cross 6%, the top of the RBI's comfort band. Here are four common assumptions about all this, and what the official data actually says.
7 November 2026 · 6 min read
India Macro
Crude is at $113. Your petrol price has not moved. Someone is paying the difference
Brent crude is around $113 a barrel, close to its highest in four years and about 76% higher than a year ago. Yet petrol in Delhi still costs ₹102.12 a litre and diesel ₹95.20, unchanged for weeks. That gap does not disappear. In September, state-run oil companies were losing about ₹8 on every litre of petrol and ₹9 on every litre of diesel they sold, roughly ₹530 crore a day, and the government gave up ₹10 a litre in tax in March to soften the blow. Here is who is paying for your full tank, and how long that can last.
29 October 2026 · 5 min read