Staying informed
How to read an IPO prospectus (DRHP) in 20 minutes
By Ashish Kumar · Published 2 November 2026 · 8 min read
The short answer: You do not need to read all of an IPO prospectus. Read five parts in this order: the offer details on the cover, Objects of the Issue, the first ten risk factors, the financials and the litigation summary. That takes about 20 minutes and tells you who is selling, where the money goes and what could go wrong.
This guide explains the documents, the reading order and the warning signs, using a real filing from October 2026 as the example. It is about understanding a company, not a tip to buy or avoid any share.
What is a DRHP, and how is it different from an RHP?
Every Indian IPO leaves a paper trail, and the names confuse people. Here is the sequence in plain words.
| Document | When it appears | What it has | What it lacks |
|---|---|---|---|
| DRHP (draft red herring prospectus) | First filing with SEBI | Business, risks, financials, plans for the money | Final price, sometimes final issue size |
| UDRHP (updated draft) | Only if the company used confidential pre-filing | The first public version of the draft | Final price |
| RHP (red herring prospectus) | After SEBI's comments, just before bidding opens | Price band, final structure, updated numbers | Final price |
| Prospectus | After bidding closes | Everything, including the final price | Nothing |
| Abridged prospectus | Sent with the application form | A short summary of the RHP | Most of the detail |
The draft is filed with the Securities and Exchange Board of India, which can ask for changes before the company moves to the RHP, as guides from Angel One and IndMoney describe. IndMoney notes that the RHP is filed after SEBI's observations are addressed and has a price band but no fixed issue price.
Some companies now file confidentially first. Zetwerk did this in March 2026 and then filed an updated draft on 13 August, ThePrint reported. You can see these "UDRHP-I" filings in SEBI's list of public issue filings, next to ordinary DRHPs and addenda.
Where do you find the prospectus?
Three places, all free:
- SEBI's website. The filings page for public issues lists drafts by date. On the day we checked, the October 2026 entries alone ran to more than 20 filings.
- The stock exchanges and the company's own investor page. These carry the RHP once bidding is near.
- The lead banks' websites. Zetwerk's abridged prospectus, for example, sits on Morgan Stanley's India offer documents page.
If you only want the highlights, open the abridged prospectus first. SEBI's rules say every application form must come with one (see the current text of Regulation 34 quoted in this SEBI consultation reprint). Zetwerk's is 15 pages. Its full RHP is far longer: the abridged version points readers to "Offer Structure" on page 658.
Which sections should you read first?
IndMoney says a useful first pass "can often be completed in about 20 to 30 minutes" if you stick to the key sections. Here is the order we suggest, with the one question each section answers.
| Order | Section | The question it answers | What to watch for |
|---|---|---|---|
| 1 | Cover page and offer details | Who gets the money? | How much is fresh issue versus offer for sale |
| 2 | Objects of the Issue (or Offer) | What will the company do with it? | Large debt repayment, vague general purposes |
| 3 | Risk Factors | What could go wrong? | Losses, customer concentration, auditor remarks |
| 4 | Financial information | Is the business getting healthier? | Profit rising while cash flow falls |
| 5 | Outstanding litigation | What legal trouble exists? | Cases against promoters, regulatory actions |
1. The cover page: fresh issue or offer for sale
The first table in any offer document splits the IPO in two. A fresh issue creates new shares, and that money goes to the company. An offer for sale lets existing owners sell their shares, and that money goes to them, not the business.
Zetwerk's abridged prospectus shows a fresh issue of up to ₹2,830 crore plus an offer for sale of up to 14.45 crore shares. IndMoney's IPO note puts the full IPO at ₹5,012 crore. So a large part of the headline figure never reached the company. That is normal, since it is how early investors cash out, but it changes what the IPO means. We walked through the numbers in our Zetwerk IPO post.
2. Objects of the Issue: follow the money
This section shows where the new money goes, often with a year-by-year schedule. Ask three things:
- How much repays debt? Zetwerk planned ₹1,300 crore to repay its own borrowings and ₹860 crore for nine subsidiaries, per its abridged prospectus and IndMoney. That is ₹2,160 crore of a ₹2,830 crore fresh issue. Paying off loans can make sense, but it is not the same as funding growth.
- How much is "general corporate purposes"? This is money with no specific job. The rules cap it at 25% of the gross proceeds, and money for unnamed acquisitions plus general purposes together at 35%. Zetwerk's document states both limits, and so does a 2022 note from law firm Cyril Amarchand Mangaldas on the SEBI amendments. IndMoney flags heavy use of these broad buckets as a warning sign.
- Did the plan change? Compare the draft with the RHP. ThePrint reported that Zetwerk's August draft proposed a ₹2,600 crore fresh issue, with ₹1,250 crore for its own debt and ₹550 crore for subsidiaries. By the RHP, both had grown. Changes are allowed, but they are worth noticing.
Our story on the ₹6,650 crore IPO where nobody is selling a single share shows how much this one section can reveal.
3. Risk Factors: read the top ten
Risk factors fill dozens of pages, and much of it is boilerplate. The abridged prospectus helps here: Zetwerk's lists "the top 10 internal risk factors" from its RHP. Those ten were specific and useful. They included:
- Losses from continuing operations in each period shown, including about ₹964 crore in FY26.
- Its top 10 customers made up 35.90% of FY26 revenue from continuing operations.
- Its statutory auditors included "certain emphasis of matters and modifications" in their reports.
Look for risks that are about this company, not risks every company has. Customer concentration, reliance on a few suppliers, auditor remarks and losses matter more than "the economy may slow down". IndMoney's advice is blunt: read every one, and be wary when they all sound generic.
4. The financials: compare cash with profit
You do not need to be an accountant. Check three lines across the years shown: revenue, profit or loss, and cash flow from operations. IndMoney points to two warning signs: a sharp jump in revenue just before the IPO, and profits rising while operating cash flow weakens. Profit is an accounting figure. Cash is what the business actually collected.
Also look at the section that compares the company with listed peers. Sometimes there is no fair comparison. Zetwerk's document said no listed company in India or globally was comparable in business and scale, so it did not compare its key metrics with peers. That is honest, but it leaves you with less to go on.
5. Outstanding litigation: the summary table
Near the end of the abridged prospectus is a table counting cases by and against the company, its directors, promoters and subsidiaries. It splits them into criminal, tax, regulatory, SEBI actions against promoters in the last five years, and material civil cases.
Read the footnotes. Zetwerk's table showed 66 criminal proceedings filed by the company, which sounds alarming until the footnote says 56 of them were under the Negotiable Instruments Act, the law used for bounced cheques. Cases against promoters, and any SEBI or exchange action, deserve more attention than cases the company itself filed.
What happens to the money after listing?
This part rarely shows up in prospectus guides. For larger issues, an outside monitoring agency checks how the IPO money is spent and reports every quarter. Since SEBI's 2022 changes, the whole fresh issue amount, including general corporate purposes, falls under this monitoring, according to the Cyril Amarchand note.
These reports are public. For example, Ellenbarrie Industrial Gases filed a monitoring agency report from Crisil Ratings with the exchanges on 13 August 2026 for the quarter ended 30 June. It confirms that general corporate purposes spending stayed within 25% of the fresh issue proceeds and says whether there was any deviation from the stated plans. If you hold a recently listed stock, search the exchange filings for "monitoring agency report" each quarter.
A quick checklist before you close the PDF
- Fresh issue versus offer for sale: who is getting the money?
- How much goes to debt, and how much to general corporate purposes?
- Did the numbers change between the draft and the RHP?
- Which of the top ten risks are unique to this company?
- Is cash flow from operations moving with profit?
- Are there cases or SEBI actions against the promoters?
- How much do the promoters keep after the IPO?
If you follow IPOs as news rather than as an investor, the same checklist turns a headline into a story. Our guides to Indian startup news and Indian business news cover where to keep up, and our Jio Platforms IPO post is another worked example.
One last thing. A prospectus is written by the company and its bankers, checked for disclosure, not for whether the price is fair. It tells you what is true and what is risky. It does not tell you what the shares are worth. This is not investment advice. If you are deciding whether to invest, consider talking to a SEBI-registered investment adviser.
Sources
- SEBI: filings for public issues (draft offer documents, UDRHPs, addenda)
- Zetwerk Manufacturing Businesses Limited: abridged prospectus (October 2026)
- Crisil Ratings: monitoring agency report for Ellenbarrie Industrial Gases, quarter ended 30 June 2026 (NSE filing)
- Cyril Amarchand Mangaldas: SEBI ICDR amendments, January 2022
- SEBI ICDR consultation reprint showing current Regulation 34 on abridged prospectus (Taxguru, November 2025)
- ThePrint: Zetwerk files updated IPO papers with SEBI (August 2026)
- IndMoney: Zetwerk IPO to open on October 15
- IndMoney: How to read a DRHP
- Angel One: What is DRHP and how to read it
Frequently asked questions
What is the difference between a DRHP and an RHP?
The DRHP is the draft a company files with SEBI before an IPO. It has no final price. The RHP is the updated version filed after SEBI's comments, and it carries the price band. Numbers can change between the two, so read the latest one.
Where can I download a DRHP or RHP?
SEBI lists draft offer documents on its website under its filings for public issues. The stock exchanges, the company and the lead banks also host them. Each IPO also has a short abridged prospectus, which comes with the application form.
Which section of a DRHP matters most?
Start with Objects of the Issue, which shows where the money goes, then the first ten risk factors. After that, check the financials, the litigation summary table and how much the promoters keep after the IPO.
Is reading the prospectus enough to decide whether to invest?
No. It tells you what the company says about itself and its risks, not whether the price is fair. This guide is not investment advice. If you are unsure, speak to a SEBI-registered investment adviser.
More from the blog
Stories worth reading next
Tech & AI
Anthropic's most powerful AI lasted 76 hours. Then the US government shut it down
On June 9, Anthropic, one of the world's top AI companies, launched its smartest AI yet, called Fable 5. Just three days later, the US government sent a single letter and forced the company to switch it off, everywhere on earth, with only 90 minutes' notice. The official reason was a safety risk. But the real story is stranger. For years, Anthropic had warned that its own AI was dangerous, and the government simply believed it. Here is what actually happened.
16 June 2026 · 4 min read
Business
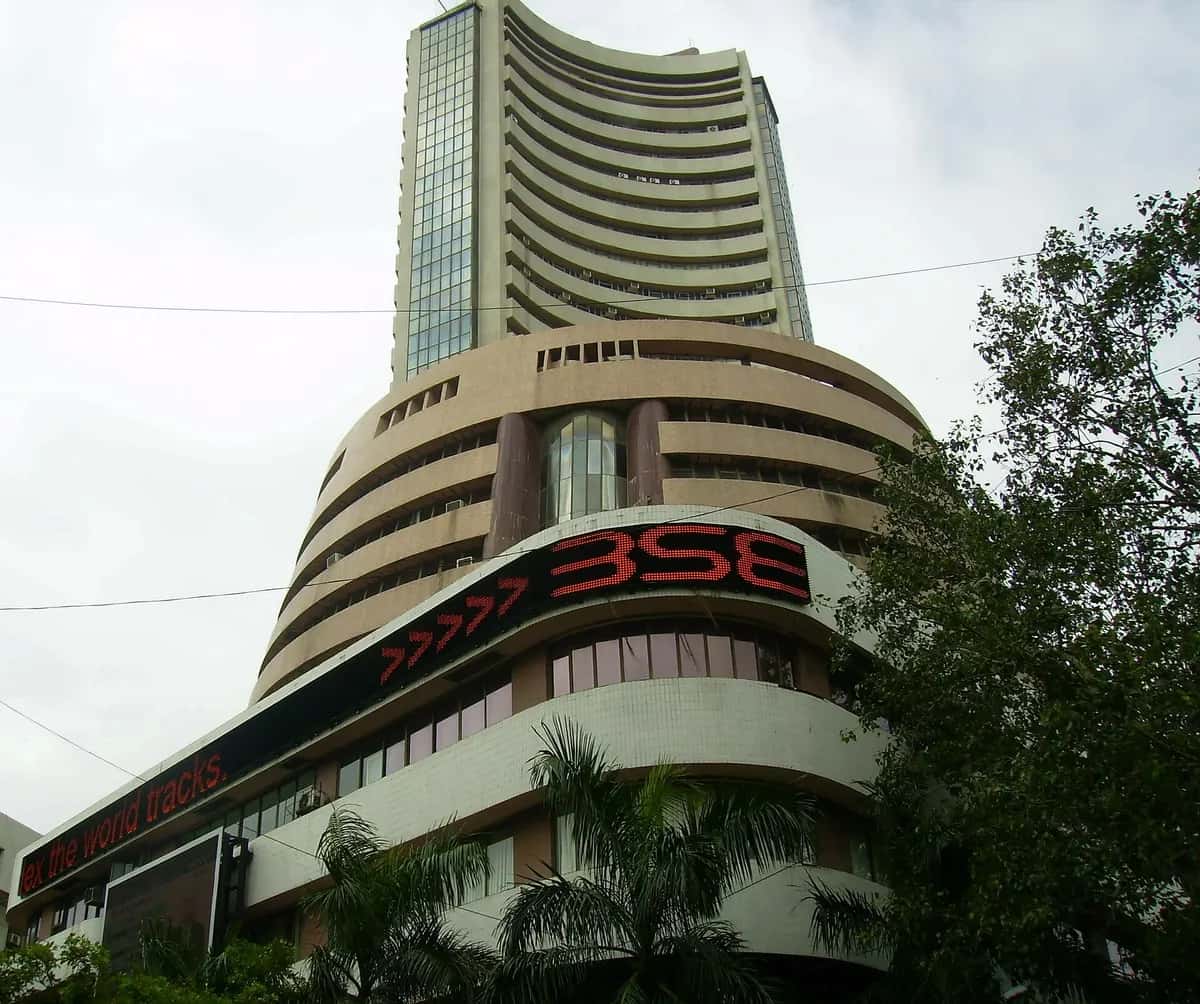
Jio Platforms listed at a 21% premium. Here is what 1.38 crore applicants actually bought
Jio Platforms opened at ₹1,358 on 28 October 2026, 21% above its IPO price of ₹1,119, and closed the day near ₹1,417. It was India's biggest IPO ever at ₹30,213 crore, and more than 1.38 crore people applied. But every rupee raised went to the company, not to early investors like Meta and Google, and most of it is going straight into paying off debt. Five plain questions about what just happened, and what it means if you got shares or missed out.
29 October 2026 · 5 min read